Insurance operations involve thousands of interconnected activities, from collecting customer information and evaluating risks to generating quotes, issuing policies, managing renewals, and processing claims.
Insurance operations involve thousands of interconnected activities, from collecting customer information and evaluating risks to generating quotes, issuing policies, managing renewals, and processing claims. While insurance technology has advanced significantly, many organizations still depend on manual data entry, disconnected applications, repetitive administrative work, and time-consuming communication between departments.
Insurance workflow automation is changing how these processes operate. By connecting business systems, automating repetitive tasks, and introducing artificial intelligence into appropriate workflows, insurance businesses can build more efficient, responsive, and scalable operations.
For insurance agencies, brokers, managing general agents (MGAs), and insurers, automation is no longer limited to simple reminders or predefined rules. Modern solutions can interpret incoming requests, extract information from documents, route tasks to appropriate teams, interact with customers, and coordinate workflows across multiple systems.
However, successful insurance workflow automation requires more than purchasing software. Organizations must understand their existing processes, identify opportunities for improvement, select appropriate technologies, integrate their systems, and establish effective human oversight.
This complete implementation guide explores how insurance workflow automation works, its most valuable applications, the technologies supporting it, and a practical framework for introducing automation into insurance operations.
Insurance workflow automation is the use of software, artificial intelligence, business rules, and system integrations to execute, coordinate, and monitor insurance-related business processes with reduced manual intervention.
It enables insurance organizations to transform repetitive, fragmented activities into connected workflows that move information between customers, employees, applications, and external service providers.
For example, consider a customer requesting an insurance quotation.
In a traditional workflow, an employee might manually collect customer information, review submitted documents, enter details into an agency management system, contact an insurer, prepare a quote, and follow up with the customer.
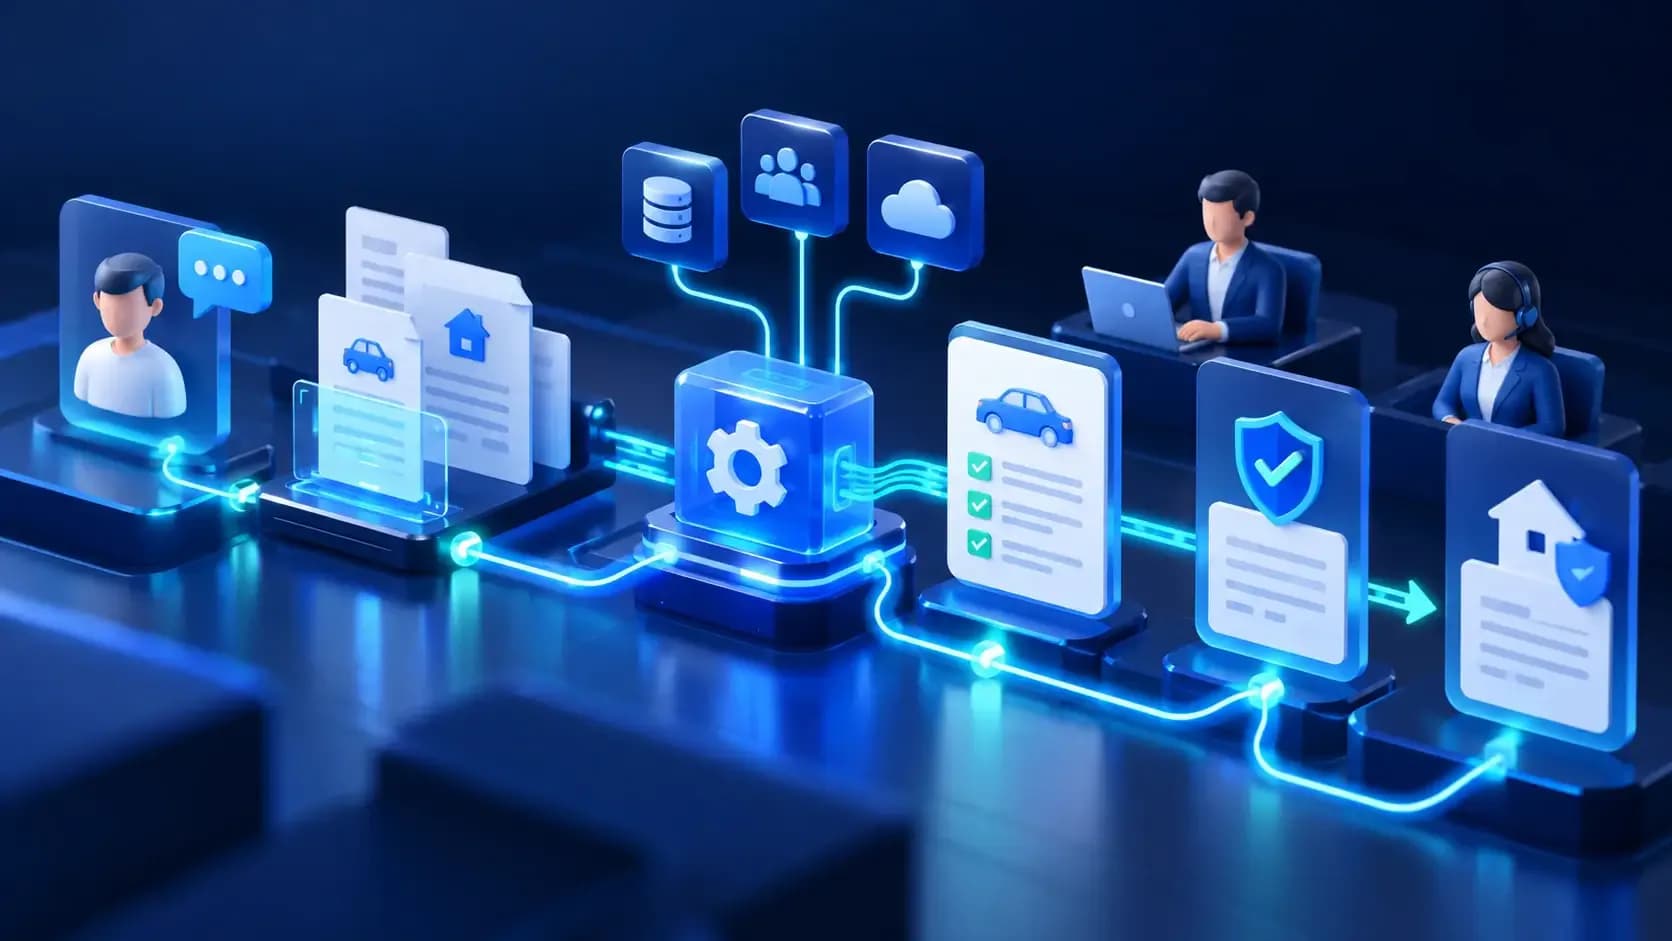
With insurance workflow automation, many of these steps can be coordinated automatically:
A customer submits a request through a website, email, or messaging channel.
An automated system collects the required information.
AI extracts relevant details from uploaded documents.
The system validates the information and identifies missing fields.
Customer and application records are created or updated in a CRM or agency management system.
A connected quoting system receives the validated request.
Available quotation results are presented to an authorized employee or customer, where permitted.
Follow-up notifications and internal tasks are triggered according to predefined rules.
Complex cases are transferred to the appropriate insurance professional.
The objective is not necessarily to eliminate human involvement. Instead, automation reduces unnecessary administrative work while allowing qualified professionals to concentrate on complex decisions, customer relationships, and activities requiring expertise.
Although the terms are frequently used interchangeably, there is a useful distinction between workflow automation and process automation.
Insurance workflow automation focuses on coordinating individual tasks, information transfers, approvals, and handoffs within an insurance operation.
Insurance process automation addresses a broader business process, potentially connecting multiple workflows, departments, applications, and external organizations.
For example, automating the assignment of incoming claims emails is a workflow improvement. Automating the broader claims administration process, including intake, document collection, validation, routing, notifications, and settlement preparation, represents a larger process automation initiative.
Both approaches complement each other, and organizations often begin with individual workflows before expanding to end-to-end automation.
Insurance organizations operate in an environment where operational accuracy, responsiveness, information security, and customer experience are essential.
A single insurance transaction may require several applications, documents, approvals, and interactions between different stakeholders.
When these activities are performed manually, operational complexity increases as transaction volumes grow.
Insurance workflow automation helps address several persistent challenges.
Insurance employees frequently spend time transferring information between applications, reviewing routine documents, creating reminders, updating records, and responding to repetitive inquiries.
These activities are necessary, but many do not require continuous manual intervention.
Automation can handle suitable repetitive tasks while preserving employee review for exceptions and important decisions.
For example, instead of manually creating renewal reminders for every policy, an automated workflow can identify approaching expiration dates, prepare notifications, and create follow-up tasks based on predefined conditions.
Manual workflows can vary between employees, departments, and offices.
One employee may follow a standardized intake checklist, while another may omit required information or use a different process.
Insurance workflow automation supports consistency by applying documented rules, validation requirements, and approval procedures across applicable transactions.
This does not eliminate errors, but it can reduce avoidable inconsistencies and make exceptions easier to identify.
Customers increasingly expect insurance businesses to respond promptly to questions, quotation requests, policy changes, and service inquiries.
Automation can acknowledge incoming requests immediately, collect required information, and direct each request toward the appropriate workflow.
For example, an AI-powered assistant may collect the details needed for a motor insurance quotation outside normal office hours.
The agency's team can then review a more complete submission when available, rather than beginning the information-gathering process from scratch.
Insurance businesses often use multiple technology platforms, including:
Customer relationship management (CRM) systems
Agency management systems (AMS)
Policy administration systems
Document management applications
Insurer and carrier portals
Rating and quotation engines
Claims management software
Email, messaging, and communication platforms
When these systems operate independently, employees must manually transfer information between them.
Connected automation workflows can coordinate information transfers through supported APIs, approved integrations, and other authorized mechanisms.
As insurance businesses expand, operational workloads typically increase.
Without process improvements, additional customers may require proportionally more administrative resources.
Automation can help organizations handle higher transaction volumes without increasing repetitive manual work at the same rate.
The actual efficiency improvement depends on workflow complexity, integration availability, data quality, and the level of human review required.
Modern insurance workflow automation combines several technological components to manage activities across different systems.
Understanding these components helps organizations choose solutions suited to their existing infrastructure.
Workflow orchestration coordinates the sequence of actions required to complete a process.
It defines when a workflow begins, which steps follow, what information must be available, and when human intervention is required.
For example, an insurance renewal workflow might begin when a policy approaches its expiration date.
The orchestration system checks customer information, creates a renewal task, requests missing documents, initiates an authorized quotation process, and schedules subsequent activities.
If information is incomplete or a quotation requires approval, the workflow pauses or routes the case to an appropriate employee.
Rules-based automation executes predefined instructions based on specific conditions.
Examples include:
Assigning commercial insurance inquiries to a specialized team.
Creating renewal tasks before policy expiration.
Flagging missing mandatory application fields.
Sending documents for approval when certain conditions are met.
Routing claims above defined thresholds for additional review.
Rules-based systems are particularly effective when processes are predictable and decision criteria can be expressed clearly.
Robotic process automation (RPA) uses software to perform repetitive interactions with digital applications.
It can be useful when an existing insurance system does not provide suitable APIs.
For example, an RPA workflow may enter approved information into a legacy application or retrieve records from a supported interface.
However, interface-based automation may be vulnerable to changes in application layouts, session requirements, or system behavior.
Where suitable APIs are available, API-based integration is generally preferable for durable, observable system connectivity.
Insurance documents often contain information that traditional rules-based systems cannot easily interpret.
AI-supported document processing can extract and organize information from:
Insurance application forms
Existing policy documents
Claims submissions
Identification documents
Vehicle registration records
Property schedules
Supporting correspondence
Extracted information should be validated before being used in sensitive or consequential processes.
AI outputs are not inherently accurate, and the required degree of verification should reflect the risk of each task.
AI insurance agents extend beyond predefined responses by interpreting requests, gathering information, selecting approved actions, and interacting with connected business tools.
For example, a properly configured AI agent may recognize that a customer wants to renew a policy, retrieve authorized account information, identify missing documents, create an internal renewal request, and transfer the conversation to a licensed professional when needed.
AI agents should operate within defined permissions, business rules, and oversight mechanisms.
They should not independently make unauthorized coverage decisions, promise binding terms, or perform regulated activities outside the organization's approved processes.
Different insurance organizations have different operational requirements. The following use cases illustrate where automation can deliver practical value.
Insurance agencies and brokers frequently receive inquiries from websites, advertising campaigns, social media, email, and messaging platforms.
Managing these requests manually can create delays, particularly when inquiries arrive outside business hours.
Insurance workflow automation can create a connected lead management process.
An AI-powered intake assistant can collect information such as insurance type, coverage requirements, preferred contact method, and relevant customer details.
The workflow can then validate required fields, identify duplicate inquiries, create CRM records, and assign qualified opportunities to the appropriate teams.
For organizations handling multiple insurance products, routing rules can distinguish between personal insurance, commercial insurance, employee benefits, and other specialized inquiries.
Practical example: A commercial insurance prospect submits a request through an agency website. The automated workflow collects business information, identifies the relevant coverage category, requests supporting documents, and prepares a structured lead record for the commercial lines team.
The result is a better-organized intake process, not an automated guarantee of eligibility or coverage.
Quotation preparation is one of the most valuable opportunities for insurance workflow automation.
Traditional quotation processes may require employees to collect customer information, review documents, enter details into multiple systems, and communicate with insurers.
Automated quotation workflows can streamline the stages surrounding rating and underwriting.
These may include:
Capturing applicant information.
Checking mandatory fields.
Requesting missing documents.
Validating submitted details.
Preparing structured quotation requests.
Sending information to supported rating engines or insurer APIs.
Organizing returned quotation data.
Routing exceptions for employee review.
Preparing customer communications.
Actual premium calculations and quotation availability depend on the connected insurer, rating engine, applicable underwriting rules, and access permissions.
An AI assistant should not invent premiums or represent estimated values as insurer-approved quotations.
Document-intensive operations are a natural starting point for insurance workflow automation.
Insurance organizations routinely process policy documents, application forms, endorsements, declarations, certificates, and claims-related files.
AI-supported document automation can classify incoming files, extract required fields, compare information, and organize documents for review.
For example, when an application is submitted, the system may identify the applicant's name, policy reference, insurance type, and relevant dates.
It can then compare extracted information against existing records and highlight discrepancies.
Human review may still be necessary when documents are unclear, information conflicts, or the requested action carries material risk.
Document automation can also assist with generating drafts from approved templates, managing document versions, and maintaining records of completed actions.
Renewal management requires timely communication, accurate records, and coordination between customers, brokers, and insurers.
Insurance workflow automation can identify upcoming renewals and initiate predefined activities.
A typical renewal workflow may include:
Identifying policies approaching expiration.
Checking existing policy information.
Preparing customer notifications.
Requesting updated details.
Creating internal renewal tasks.
Preparing information for re-quotation.
Recording customer responses.
Escalating unresolved renewals.
Automation can improve follow-up consistency while keeping coverage changes, binding, and other controlled activities subject to appropriate authorization.
Claims workflows often involve extensive information collection, supporting evidence, customer communication, and coordination among multiple parties.
Automation can assist with initial claims registration, document requests, status notifications, and internal assignment.
For example, an automated claims intake system may collect incident details, request photographs or supporting documents, create a claim record, and route the submission for review.
AI may help summarize submitted information or identify missing documentation.
However, claims coverage determinations, fraud findings, liability assessments, and settlement decisions should remain governed by appropriate controls and authorized personnel.
Insurance customers regularly ask questions about policy documents, payment procedures, renewal dates, coverage terminology, and service requests.
AI-powered customer service workflows can respond to suitable routine questions using approved information sources.
When connected securely to operational systems, authorized assistants may retrieve account-specific information or initiate permitted service actions.
A well-designed workflow should recognize uncertainty, provide transparent explanations, and transfer sensitive or complex requests to a human representative.
Insurance marketing automation helps agencies manage prospect engagement and existing customer communications.
Common applications include lead nurturing, campaign segmentation, follow-up reminders, and permitted cross-selling communications.
For example, a customer who requests commercial property insurance may receive relevant follow-up communications based on the organization's approved marketing rules.
Consent, communication preferences, applicable privacy requirements, and recordkeeping obligations must be considered when designing these workflows.
Insurers and MGAs can use insurance workflow automation to improve the preparation and routing of underwriting submissions.
Automated workflows can collect applicant information, verify document completeness, categorize submissions, and identify cases that require specialized underwriting review.
AI may assist with extracting relevant information from loss runs, schedules, and application materials.
Nevertheless, automated extraction and summarization should be distinguished from authorized underwriting decisions.
The goal is to provide underwriting professionals with organized, reliable information so they can evaluate submissions more effectively.
Choosing insurance automation software requires evaluating more than the number of available features.
A suitable solution must support the organization's workflows, existing technology environment, security requirements, and operational responsibilities.
Integration is particularly important because insurance operations depend on multiple internal and external platforms.
Look for support for documented APIs, webhooks, authentication mechanisms, controlled data exchange, and error handling.
The availability of an integration should be verified rather than assumed.
For example, an agency management system may offer different integration capabilities depending on its product version, licensing arrangement, or API access permissions.
Insurance workflows vary between organizations.
Software should support configurable validation rules, routing conditions, approval stages, exception handling, and escalation procedures.
Rigid workflows may create additional manual work when business requirements change.
Where document automation is required, evaluate supported document formats, extraction accuracy, validation controls, and handling of low-confidence results.
A system that extracts data quickly but introduces frequent errors may not improve the overall process.
Insurance automation software should allow employees to inspect relevant information and approve consequential actions.
Important capabilities include configurable approval requirements, reviewer assignments, action histories, and clear mechanisms for correcting errors.
Insurance platforms often process personal, financial, and commercially sensitive information.
Organizations should evaluate encryption, identity management, access restrictions, logging, retention controls, and third-party data processing arrangements.
Workflow monitoring helps teams understand whether automation is performing as intended.
Useful indicators include processing time, exception frequency, failed integrations, manual review volume, and completed transactions.
An automation system should remain manageable as transaction volumes, workflows, integrations, and organizational needs change.
Consider how workflows are updated, tested, documented, deployed, and supported.
These operational factors may matter more over time than an impressive initial demonstration.
Traditional automation and AI agents are complementary technologies, but they perform different functions.
Capability | Traditional Automation | AI Insurance Agents |
|---|---|---|
Core approach | Predetermined rules and sequences | Language understanding and tool-assisted workflows |
Input handling | Typically structured data | Structured and unstructured inputs |
Customer interaction | Forms, templates, predefined messages | Contextual conversations within defined boundaries |
Document interpretation | Templates and configured extraction | AI-assisted extraction and interpretation |
Workflow decisions | Explicit business rules | Contextual routing with permissions and safeguards |
Predictability | High for stable, defined inputs | Variable, requiring evaluation and controls |
Best suited for | Repeatable administrative tasks | Conversational intake and information-intensive workflows |
For example, a rules-based workflow can reliably create a renewal task when a policy reaches a specified date.
An AI agent may assist when the customer replies with an unstructured message explaining that the insured property has changed.
The agent can identify the request, collect additional information, and route the matter to an authorized employee.
The strongest implementations often combine deterministic automation for reliable system operations with AI for interpretation and interaction.
This hybrid model helps organizations benefit from AI without unnecessarily exposing critical processes to unpredictable outputs.
A successful implementation begins with operational requirements rather than technology selection.
The following framework can be adapted to agencies, brokers, MGAs, insurers, and insurance technology providers.
Document how work currently moves through the organization.
Identify where requests originate, who processes them, which applications are used, what approvals are required, and how completion is recorded.
For each workflow, document:
The triggering event.
Required customer and business information.
Systems and data sources.
Employee responsibilities.
Business rules and approvals.
Common exceptions.
Current processing time.
Error and rework patterns.
For example, mapping a quotation workflow may reveal that employees enter the same information into multiple systems or repeatedly request documents that could have been collected during intake.
These observations become candidates for automation.
Not every insurance workflow should be automated immediately.
Start with processes that are repetitive, measurable, reasonably standardized, and sufficiently supported by available data.
A simple prioritization method is to evaluate each process against five criteria:
Criterion | Evaluation question |
|---|---|
Frequency | How often does this workflow occur? |
Manual effort | How much employee time does it require? |
Complexity | How predictable are the steps and exceptions? |
Integration feasibility | Can the required systems exchange information? |
Operational risk | What happens if automation produces an incorrect result? |
A workflow with high frequency, substantial manual effort, reliable integrations, and manageable risk is often a strong initial candidate.
Document classification, lead intake, and internal task routing are common examples worth evaluating.
Each initiative should have measurable objectives.
Examples include reducing average intake processing time, improving application completeness, decreasing duplicate entry, or accelerating internal assignment.
Avoid setting targets without first measuring current performance.
Useful baseline metrics include:
Average handling time per request.
Number of manual steps.
Percentage of incomplete submissions.
Frequency of data corrections.
Time from inquiry to employee assignment.
Percentage of cases requiring escalation.
These measurements provide a basis for evaluating whether automation creates actual operational improvement.
Once the current process is understood, define how the automated workflow should operate.
Specify the triggering event, required inputs, validation steps, system integrations, and expected output.
Also define how the workflow handles exceptions.
Give every enquiry a clearer next step.
See how Stack.insure connects customer conversations, quote comparisons and team follow-up around the way your insurance business works.
For example, consider an AI-supported insurance inquiry workflow:
Customer inquiry → AI-assisted information collection → Data validation → CRM update → Authorized quotation request → Broker review → Customer follow-up
Each transition requires a defined responsibility.
If the CRM is unavailable, should the workflow retry, create an alert, or pause the process?
If the customer provides conflicting information, should the system request clarification or escalate the matter?
These questions should be answered during workflow design rather than after deployment.
Integrations determine whether insurance workflow automation can operate across the organization's existing technology stack.
Identify every system that must send, receive, or update information.
Review available APIs, authentication methods, data formats, access restrictions, and vendor requirements.
Where insurance-specific data standards are relevant, consider established industry frameworks and supported standardized formats.
Avoid relying on unsupported assumptions about access to insurer platforms, agency management systems, or external rating engines.
An integration that cannot be authorized, maintained, or monitored should not be treated as production-ready.
Insurance automation should be designed around appropriate security and operational controls from the beginning.
This is particularly important when AI systems process customer documents, policy details, or sensitive business information.
Define:
Which users and automated services can access each system.
What data may be collected and retained.
Which external providers may process information.
Which actions require human approval.
How AI-generated outputs are verified.
How workflow activity is logged.
How errors, incidents, and exceptions are managed.
Organizations introducing AI can use recognized risk management guidance, such as the NIST AI Risk Management Framework, as a reference for evaluating AI-related risks.
Compliance obligations vary by jurisdiction, insurance product, business model, and applicable regulations. Legal and compliance professionals should review requirements relevant to each deployment.
Begin with one clearly defined workflow.
A controlled pilot makes it easier to evaluate integrations, employee adoption, exception handling, and data quality before expanding.
For example, an agency might pilot automated intake for a specific insurance product while preserving its existing quotation and approval procedures.
Test the workflow using representative scenarios, including incomplete applications, conflicting information, duplicate requests, unavailable systems, and unusual customer inquiries.
For AI-powered workflows, testing should also cover unsupported requests, inaccurate extraction, prompt injection attempts, and situations where the system must decline or escalate an action.
Automation changes how employees interact with information and systems.
Teams should understand which tasks are automated, which remain manual, and when intervention is required.
Provide clear procedures for reviewing AI outputs, correcting errors, handling exceptions, and reporting unexpected behavior.
Successful adoption depends on whether employees trust the workflow and understand its limitations.
After successful testing, expand the workflow to an appropriate production environment.
Track operational performance and compare results with the baseline established earlier.
Monitor failed tasks, incorrect routing, integration problems, processing times, and employee corrections.
Use these observations to improve business rules, instructions, user interfaces, and system integrations.
Insurance workflow automation should be treated as an ongoing operational capability rather than a one-time software installation.
To understand how these components fit together, consider a hypothetical insurance agency automating customer intake and quotation preparation.
A prospective customer visits the agency's website and starts a conversation with an AI insurance assistant.
The assistant identifies the type of insurance requested and collects the required information.
The customer uploads relevant documents.
An AI-supported processing service extracts selected information and flags missing or unclear details.
The system requests clarification when necessary.
Validated information is organized into a structured application record.
Business rules check mandatory fields, data formats, duplicate submissions, and workflow eligibility.
The orchestration layer sends approved information to the connected CRM or agency management system.
Where an authorized quotation integration exists, the workflow may submit the information to a supported rating or insurer system.
The assigned insurance professional reviews the submission, assesses exceptions, and handles actions requiring professional judgment or authorization.
Once the permitted actions are completed, the workflow records the outcome, prepares appropriate customer communications, and updates internal tracking.
This example illustrates a connected approach in which customer interaction, document handling, data validation, existing business applications, and employee responsibilities operate within a coordinated process.
It is an architectural illustration rather than a claim that every insurance system supports these integrations out of the box.
Insurance businesses generally have two broad implementation options: adopting a predefined software product or developing a customized automation environment.
Preconfigured insurance automation software may be suitable for organizations with relatively standardized processes.
Potential advantages include established functionality, faster initial configuration, and access to vendor-managed updates.
However, organizations should evaluate whether the platform can support their actual workflows and existing systems.
A ready-made solution may be less suitable when the organization depends on unusual approval processes, specialized insurance products, or proprietary infrastructure.
Custom automation is designed around an organization's particular requirements.
It may incorporate existing applications, specific business rules, branded AI assistants, specialized integrations, and organization-specific workflows.
Custom implementations can be especially relevant for insurance brokers, MGAs, and insurers with complex operational environments.
Stack.insure focuses on custom AI insurance agents and insurance automation infrastructure that can be designed around an organization's existing systems and operational requirements.
Rather than assuming every insurance business should follow the same workflow, the custom implementation approach begins by defining how the business operates, identifying available integrations, and establishing the controls required for connected automation.
The appropriate choice depends on system complexity, customization needs, budget, internal technical resources, data governance, and long-term maintenance expectations.
Insurance workflow automation costs vary considerably based on the complexity and scope of the implementation.
A simple internal workflow using an existing automation platform may require substantially less investment than a custom system connecting several insurance applications and AI services.
Key cost drivers include:
A basic notification workflow involves fewer components than an end-to-end quotation process with document extraction, validation, insurer integrations, and human approvals.
Connecting multiple systems can increase development, testing, maintenance, and vendor access requirements.
Legacy applications and restricted APIs may add further complexity.
Conversational AI, document analysis, retrieval systems, and agentic workflows may introduce model usage costs, evaluation requirements, and ongoing monitoring.
Hosting arrangements, cloud infrastructure, data storage, security controls, and disaster recovery requirements influence ongoing costs.
Insurance workflows must be maintained as internal processes, external systems, and regulatory requirements change.
Support responsibilities should be defined before implementation.
Commercial arrangements may involve subscriptions, implementation fees, private licensing, managed services, or custom development contracts.
Organizations should clarify source code access, intellectual property rights, data ownership, hosting responsibility, modification rights, and termination arrangements.
For a reliable estimate, map the intended workflow and identify the actual integrations before requesting a quotation.
Return on investment should be calculated using measurable improvements rather than broad assumptions about AI productivity.
A useful starting point is to measure the labor effort associated with the existing workflow.
Consider an illustrative insurance operation that processes 2,000 requests per month.
Suppose the average manual handling time is 12 minutes per request.
That represents:
2,000 requests × 12 minutes = 24,000 minutes, or 400 hours per month.
If a redesigned workflow reduces average handling time to 5 minutes, the new workload becomes:
2,000 requests × 5 minutes = 10,000 minutes, or approximately 167 hours per month.
The difference is approximately 233 hours of processing capacity per month.
This is a hypothetical example, not an industry benchmark or guaranteed result.
The organization must still account for exception handling, quality checks, monitoring, system costs, and whether the reduced handling time translates into actual financial savings.
A practical ROI framework is:
ROI (%) = [(Total Financial Benefits − Total Automation Costs) ÷ Total Automation Costs] × 100
Potential financial benefits may include avoidable administrative costs, reduced correction effort, incremental contribution from additional completed business, and other measurable improvements.
Avoid counting the same benefit twice.
Time released from repetitive work is valuable, but it should not automatically be treated as a direct reduction in payroll expense.
Automation depends on reliable information.
Duplicate customer records, inconsistent formats, missing policy details, and inaccurate documents can produce unreliable outcomes.
Data validation and ownership procedures should be established before automating downstream actions.
Some insurance platforms have limited integration capabilities.
These limitations can make automation more expensive or restrict which activities can be connected.
A realistic architecture should reflect actual system capabilities.
Not every insurance decision is appropriate for autonomous execution.
Underwriting judgments, policy binding, claim determinations, and other consequential activities may require professional review and specific authorization.
Automation boundaries should be designed according to business risk.
Many workflows perform well under ideal conditions but fail when information is incomplete or systems are unavailable.
Effective implementations need reliable retry mechanisms, alerts, human escalation, and recovery procedures.
AI agents can produce inaccurate interpretations or unsupported responses.
Organizations should evaluate output quality using representative test cases and continue monitoring after deployment.
Automation requires ongoing responsibility for workflows, integrations, permissions, incidents, and changes.
Without clear ownership, even technically successful systems can become difficult to maintain.
The following principles help organizations improve implementation outcomes.
Start with an operational problem. Identify specific work that needs improvement before selecting technologies.
Prioritize measurable workflows. Choose processes where baseline performance and implementation results can be evaluated.
Integrate with existing systems. Avoid creating disconnected tools that introduce additional manual work.
Keep consequential decisions controlled. Use appropriate approval processes and professional oversight.
Treat AI output as information requiring suitable validation. Apply stronger controls when incorrect outputs could create material consequences.
Design for exceptions. Incomplete requests, integration failures, and unusual cases should have clear handling procedures.
Build security into the architecture. Access controls, data handling, logging, and vendor assessments should not be afterthoughts.
Plan for ongoing maintenance. Workflows should be documented, tested, and updated as systems and business processes evolve.
These practices are relevant whether an organization adopts ready-made insurance automation software or commissions a customized implementation.
Insurance automation is evolving from isolated task execution toward more connected, context-aware systems.
Traditional automation tools remain valuable for predictable operations. AI increasingly complements these tools by interpreting unstructured information, supporting conversations, and coordinating approved activities.
Several developments are shaping this direction.
AI agents can become more useful when they are connected to authorized business tools rather than functioning as standalone chat interfaces.
With appropriate permissions, such agents can assist with intake, record retrieval, workflow initiation, and employee handoff.
AI-supported extraction and classification can make document-heavy operations easier to organize.
However, verification remains essential, particularly when extracted information influences coverage, eligibility, or financial outcomes.
A practical direction for insurance operations is the combination of automated preparation and human decision-making.
AI can organize information and initiate permitted tasks while insurance professionals focus on judgment, customer relationships, and exceptions.
Organizations may increasingly favor architectures that allow individual capabilities to connect through APIs and replaceable components.
This approach can support integration flexibility, although its success depends on system compatibility and governance.
As AI becomes more involved in operational workflows, organizations need clear controls over accuracy, data access, accountability, and permissible actions.
Responsible deployment is an important part of sustainable insurance automation.
The future is not necessarily an insurance organization without employees. It is an organization where employees and connected technology work together with clearer responsibilities and less unnecessary friction.
Insurance workflow automation is the use of software, business rules, artificial intelligence, and integrations to coordinate repetitive insurance processes with reduced manual intervention. Common applications include lead intake, quotation preparation, document processing, renewals, claims administration, and customer service.
Insurance workflow automation connects a triggering event to a series of predefined or AI-assisted actions. These actions may include collecting information, validating data, updating business systems, assigning tasks, requesting approvals, and notifying customers or employees.
Potential benefits include reduced manual effort, more consistent processing, faster request routing, improved data handling, and better visibility into operations. Actual results depend on workflow design, data quality, system connectivity, employee adoption, and appropriate oversight.
Workflow automation focuses on coordinating tasks and handoffs within a process. Insurance process automation may cover a broader end-to-end business activity involving multiple departments, workflows, and systems.
Yes. AI can support insurance workflows by interpreting customer inquiries, extracting document information, identifying missing details, and helping coordinate approved activities. However, AI outputs require suitable validation, and consequential actions may require authorized human review.
Organizations should generally evaluate repetitive, measurable, standardized, and lower-risk activities first. Lead intake, document classification, internal task routing, and renewal reminders are common candidates. The best starting point depends on the organization's existing processes and technology environment.
Insurance document automation uses software and, where appropriate, AI to classify, extract, validate, organize, and prepare information from insurance-related documents. It can reduce repetitive handling while preserving review procedures for uncertain or sensitive information.
Yes, when suitable integration capabilities and authorization are available. Implementations may use APIs, webhooks, middleware, or other supported methods. Integration feasibility depends on the specific CRM, agency management system, vendor permissions, and technical requirements.
Insurance workflow automation can benefit smaller agencies when it addresses repetitive activities that consume meaningful employee time. Small organizations may begin with narrowly scoped workflows rather than adopting a complex automation environment immediately.
Costs depend on workflow complexity, required integrations, AI capabilities, hosting arrangements, security requirements, licensing, and maintenance. Organizations should define their intended processes and technical dependencies before comparing implementation proposals.
A basic insurance chatbot generally answers questions or follows predefined conversation flows. An AI insurance agent may also interpret requests, collect information, use authorized tools, and coordinate connected workflows. Both require appropriate controls, especially when handling sensitive customer information.
Automation can reduce administrative work and support faster processing, but it does not eliminate the need for insurance professionals. Activities involving regulated advice, judgment, customer relationships, and consequential decisions may require authorized human involvement.
Implementation time varies according to workflow complexity, integration readiness, data quality, testing requirements, security review, and organizational approvals. A narrowly scoped workflow may be implemented more quickly than a multi-system insurance automation program.
Common measures include average handling time, processing capacity, exception rates, data correction frequency, workflow completion rates, customer response time, and operational costs. Results should be compared against a reliable pre-implementation baseline.
Important considerations include workflow configurability, system integrations, security, human approval mechanisms, document handling, monitoring, scalability, maintainability, and total ownership costs.
Stack.insure develops custom AI insurance agents and connected automation infrastructure for insurance businesses. Its approach focuses on understanding operational requirements, designing suitable workflows, evaluating existing integrations, and supporting tailored implementation needs rather than assuming every organization requires the same software configuration.
Insurance workflow automation provides a practical opportunity for insurance organizations to improve the way information, tasks, and decisions move across their operations.
From lead qualification and quotation preparation to document processing, renewals, and customer service, connected workflows can reduce repetitive administrative effort and support more consistent execution.
However, effective automation is not simply about introducing AI or replacing manual tasks with software.
It requires a clear understanding of existing processes, reliable system integrations, measurable objectives, appropriate governance, and well-defined responsibilities between technology and employees.
For insurance agencies, brokers, MGAs, and insurers, the most sustainable approach is often to begin with a clearly defined operational challenge, implement a controlled workflow, measure its performance, and expand where the results justify further investment.
As AI capabilities evolve, insurance workflow automation will increasingly combine deterministic systems, intelligent information processing, and connected AI agents.
Organizations that approach this transition with strong operational design and appropriate oversight will be better positioned to build adaptable insurance technology environments.
Stack.insure helps insurance businesses explore this transition through custom AI insurance agents, connected workflows, and tailored insurance automation infrastructure. By focusing on existing systems, specific business requirements, and practical implementation considerations, organizations can move toward AI-enabled operations without assuming that every process needs to be rebuilt.
Looking to connect AI agents with your insurance operations?
Explore how Stack.insure can help design custom automation workflows around your business processes, existing applications, and implementation requirements.
Build connected insurance operations with AI agents, workflow automation, and infrastructure designed around your business.